India’s push toward renewable energy has created several compelling corporate stories over the past decade, and few are as widely followed by retail investors as the country’s leading wind turbine manufacturer. Movement in the Suzlon Share Price has become a regular talking point among traders who track the broader clean energy theme, particularly given the company’s dramatic journey from near financial collapse to renewed profitability. At the same time, many of the same investors also keep an eye on the Idea Share Price, since both counters share a reputation as high-volume, widely held stocks that have each delivered their own version of a corporate revival. This piece focuses specifically on what underlies the wind energy company’s current position and what factors are likely to shape its path going forward.
From Heavy Debt to a Cleaner Balance Sheet
This company has had a chequered past with aggressive overseas expansion using borrowed capital, leaving it with a debt-flooded balance sheet when foreign markets turned unfavourable. Years of restructuring later, a debt-to-equity conversion and strategic divestments saw the company lighten its debt load and improve its capital structure. While a painful process for equity shareholders who remained invested for the long duration of the ordeal, the company emerged with a healthy balance sheet and flexible capital structure.
This turnaround has formed the basis for the bullish thesis on the stock as a company that went from having doubts on its survival to currently posting positive net worth, consistent profits over the last couple of years, and healthy returns on equity when compared to many of its peers in the capital goods space. This has contributed to the stock finding able buyers at various points in time, allowing it to trade at higher levels.
Order Book Strength and Policy Tailwinds
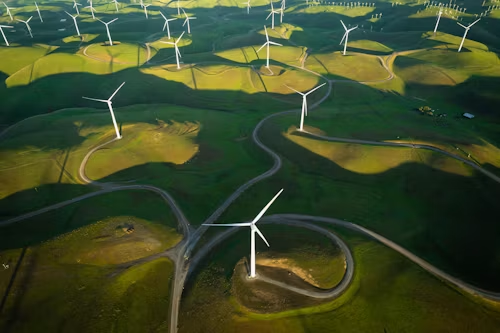
The company has also been able to benefit from its own turnaround as the order book has remained strong on the back of India’s push to add renewable energy capacity. Both public sector utilities and private developers have placed significant orders across wind turbine installations in recent years, with the government promoting the clean energy transition.
The company’s vertically-integrated approach allows it to reap rewards at every stage of the project lifecycle from design, installations to operations and maintenance services. By not stopping at the equipment sales, the company is able to benefit from enhanced value capture.
Government incentives for renewable energy addition coupled with state-level power purchase agreements to buy wind energy have also contributed towards a healthy order-book for the company. The pro-renewables push from the central government is likely to remain supportive for the sector given the climate change commitments made by the country.
Recent Price Weakness and Its Drivers
While the stock has been on a roll for the last few years, it has had its fair share of corrections as it has struggled to maintain its highs over the last year. The recent weakness can be attributed to profit-booking after a long bull-run in the stock, rising input costs squeezing margins, and overall caution in the market towards mid-cap and small-cap stocks after outperforming for a prolonged period of time.
Block-dealings and promoter and institutional investor-related activity have also sometimes cast a shadow over the stock. While such activity shouldn’t necessarily be a concern for investors, it’s important to differentiate between temporary sentiment-driven weakness and a permanent shift in fundamentals.
Valuation Considerations for a Re-Rated Stock
On the back of its turnaround, the stock has moved up many multiples on the back of its improved fundamentals. This means that while the company has shed its old troubled image, the new improved stock comes with higher valuation expectations when compared to where it traded during its distressed period.
This makes it more susceptible to disappointment on the earnings front, slowdown in order inflows or any weakness in its margins. While the long-term bull-case for the stock remains intact, it’s important for investors to tempered expectations when it comes to the valuation multiples on offer.
What Investors Should Watch Going Forward
For investors tracking this stock, order inflows or the lack thereof remains a key watch-out as large-scale wind energy tenders are likely to give an idea of how the company is likely to perform in the medium-term.
Any delays in execution timelines or order inflows can also impact the stock in the shorter term.
Movements in margins on the back of rising input costs will also be important to watch out for.
Rising competition in the wind energy equipment space in India could also eat into the company’s market share over time, while policy changes in the sector at the central and state level can also impact the company’s performance.
A Long-Term View on a Cyclical Growth Story
For investors looking to take a call on the stock, it’s important to look at the bigger picture as far as the long-term growth prospects are concerned rather than get fazed by near-term corrections. India’s renewable energy push is a multi-decade growth story, and companies that have the requisite manufacturing setup and an improved capital structure are well-placed to benefit. That said, a careful evaluation of quarterly results, order-book developments, and commentary from company management will be needed before taking a view on this stock or any similar stock in the renewable energy space.